
If you want to scrap a car with finance owing in NZ, you may be able to do so, but the outstanding finance needs to be sorted with the lender before the vehicle can be properly disposed of. Get the current settlement figure from your finance company and tell the wrecker about the outstanding loan before accepting an offer.
Before the wrecker collects your car, make sure you have agreed on exactly how the outstanding finance will be paid. Once the lender confirms the loan has been settled, check that the PPSR security interest has been removed. You can then complete the required NZTA steps to dispose of the vehicle or cancel its registration.
Before You Call a Wrecker: Have These 5 Details Ready
Before you call a car wrecker about a financed vehicle, have these five details ready: your lender name and account number, current settlement figure, 17-character VIN, registration number, and whether an insurer has written the car off. You can find most of this information on your loan documents, vehicle paperwork, or the car itself.
Having these details ready helps the wrecker check your vehicle quickly and give you a clearer idea of the next steps. Most importantly, get the current settlement figure directly from your lender, rather than using the balance shown on an old statement.
If the car was written off by an insurer, mention this when you request a quote. It can affect how the vehicle is handled and what paperwork is required. A professional wrecker can then explain the process and arrange the vehicle collection once the finance requirements are clear.
Can You Scrap a Car With Finance Owing in NZ?
You can scrap a car with finance owing in New Zealand but you cannot simply hand the vehicle to a wrecker while the lender still has a security interest over it. Finance companies commonly register their interest on the Personal Property Securities Register (PPSR).
Before arranging car removal, contact your lender, get the current settlement figure, and confirm how the finance will be cleared. A professional car wrecker can then assess your vehicle and explain the payment and collection process.
Once the finance is settled and the lender’s PPSR interest is discharged, you can proceed with the vehicle disposal and required NZTA steps.
What Actually Goes Wrong If You Ignore the Finance?
Ignoring the finance can leave you with no car, no payment and the same loan to repay. If a lender still has a registered security interest on the PPSR, it may have rights over the vehicle even after you hand it to a wrecker.
This can create serious problems including:
- The wrecker may face a claim over the vehicle or payment.
- Your outstanding finance may still need to be paid.
- You could end up in a dispute with the wrecker.
Before selling your financed car for scrap, contact your lender first and confirm how the finance will be cleared. This simple step can prevent costly problems later.
Why reputable wreckers ask about finance
Reputable wreckers ask about outstanding finance before confirming a price because a registered security interest can affect the vehicle after sale. They need to know the finance status before buying or removing the car.
If finance is owing, provide the details upfront so the wrecker can explain the next steps and avoid delays.
What happens to the finance when the car is scrapped?
Scrapping your car does not clear the loan. The wrecker takes the vehicle but the finance remains until the lender is paid in full.
Step 1: Get the current settlement figure
Call your lender and ask for the exact settlement amount to close the loan. Do not rely on your last loan statement, as interest or fees may have changed the amount.
Step 2: Confirm how the lender wants payment
Ask whether the wrecker can pay the lender directly or whether you must make the payment yourself. Get the correct bank details and payment reference before the car is collected.
Step 3: Confirm the finance is cleared
After payment, get written confirmation that the loan is settled. Check the PPSR later to make sure the registered security interest has been removed.
How to scrap a car with finance owing in NZ: full process
You can scrap a car with finance owing but scrapping the vehicle does not clear the loan. Before booking car removal, confirm the finance, get a wrecker’s offer and agree how the remaining loan will be handled.
1. Confirm the finance is active
Check your loan documents or contact the lender to confirm the finance is still active and whether the car has a registered security interest.
2. Get the settlement figure
Ask the lender for the current settlement figure in writing. This tells you exactly what is needed to close the finance.
3. Confirm the payment process
Ask the lender how the finance must be paid and whether the wrecker can pay the lender directly. Confirm the payment details before collection.
4. Get a cash offer
Give the wrecker the car’s make, model, year, condition, location, and running status. Damaged and non-running vehicles can still have value through usable parts and scrap metal.
Give the wrecker the car’s make, model, year, condition, location, and running status. Damaged and non-running vehicles can still have value through usable parts and scrap metal. Our NZ scrap car prices guide shows what affects that value.
5. Compare the offer with the settlement figure
Check the wrecker’s offer against the settlement figure. If the offer does not cover the finance, you will need to arrange payment for the remaining balance.
6. Agree how the finance will be cleared
Before collection, confirm who will pay the lender, how the payment will be made, and how any remaining finance will be handled.
7. Keep the paperwork
Keep your settlement statement, payment confirmation, lender release, and wrecker receipt. Record the VIN and odometer reading when the vehicle is collected.
8. Notify NZTA
After disposing of the vehicle, complete the required NZTA notification so the vehicle is no longer recorded in your name.
If your financed car was written off by an insurer
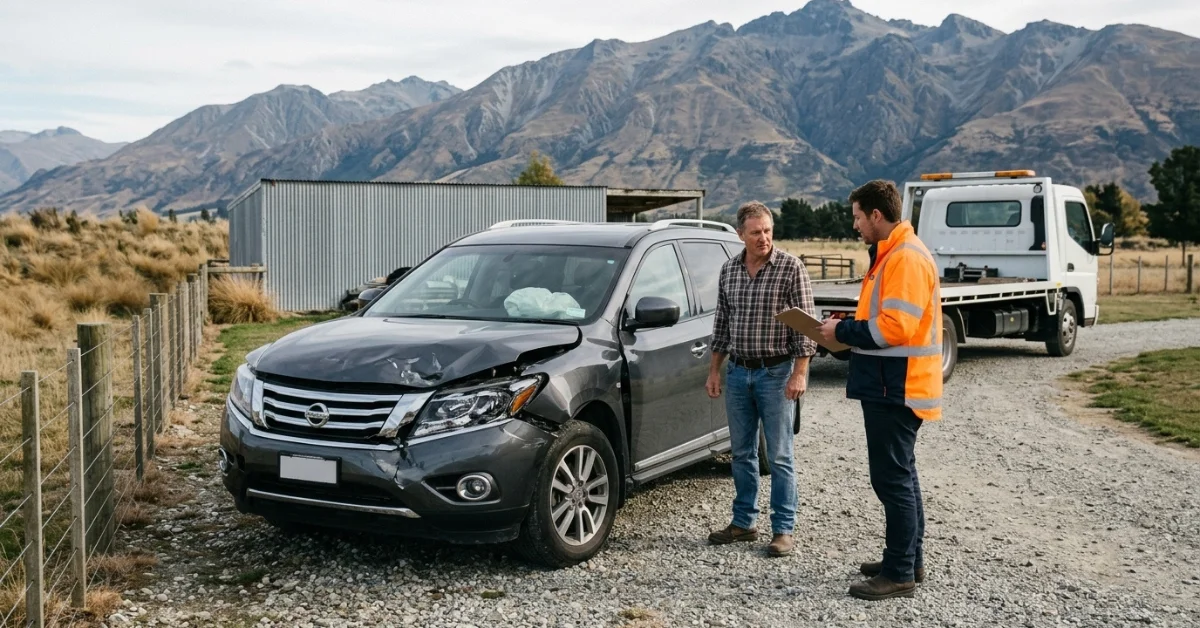
If your financed car is written off, the insurer will usually deal with the lender first. If the insurance payout is less than the remaining finance, you may still have a shortfall to pay.
If the insurer takes the vehicle as part of the claim, you cannot sell or scrap it yourself. If you want to keep the wreck, arrange this with the insurer before disposal.
Check your finance agreement, insurance policy, and any GAP insurance before paying the shortfall yourself. GAP cover may help with the difference between the insurance payout and the remaining finance, depending on your policy terms.
What If You Owe More Than Your Car’s Value?
If your finance settlement is higher than the car’s value, selling or scrapping the vehicle will not clear the full loan. You need to decide how the remaining finance will be handled before arranging the collection.
Option 1: Sell or scrap the car
Get a cash offer from a wrecker and use the proceeds toward the finance. If the offer is below the settlement figure, you remain responsible for the difference.
Option 2: Ask for hardship help
If an unexpected event has made your repayments difficult, you may be able to ask your lender for a hardship variation. This can change the repayment terms, depending on your circumstances and the lender’s decision.
Option 3: Voluntary surrender
You can ask the lender to take the vehicle back and sell it. However, the sale proceeds may not clear the finance, leaving you responsible for the remaining debt.
Before choosing an option
Compare the wrecker’s cash offer, your settlement figure, and your ability to cover any remaining finance. If you are struggling with repayments, speak with your lender before arranging vehicle removal.
Paperwork for Scrapping a Financed Car in NZ
PPSR and NZTA handle different parts of the process. Clearing the finance does not update the vehicle’s NZTA records, and notifying NZTA does not remove the finance.
Finance paperwork: PPSR
After the finance is paid, the lender must discharge the registered security interest. Check the PPSR using the vehicle’s VIN after settlement to make sure the registration has been removed.
If the lender does not remove it
You can formally request the discharge. If the lender does not respond within the required period, you may be able to lodge a change demand through the PPSR process.
Vehicle paperwork: NZTA
When you sell or dispose of the vehicle, you must notify NZTA. If the vehicle is being destroyed and will not return to the road, registration may also need to be cancelled using MR15.
Refunds and final checks
When cancelling registration, return the plates and check whether you are entitled to a refund for unused licence fees. If RUC has been paid in advance, ask NZTA about any applicable refund.
Before the car leaves, remove your belongings, photograph the VIN and odometer, cancel the insurance and remove the vehicle from any tolling account.
Frequently Asked Questions
Can you scrap a car with finance owing in New Zealand?
Yes, but deal with the lender first. Get the settlement figure and confirm how the registered security interest will be cleared before the car is collected.
Is it illegal to scrap a car with finance on it?
You should not dispose of a vehicle with a registered security interest without the secured party’s permission. The lender may have rights over the vehicle even after it has been passed to someone else.
What happens to the car loan when you scrap the car?
The loan does not end when the car is scrapped. The finance must still be paid until the lender confirms the loan is settled.
Can a car wrecker pay off the finance?
Sometimes. Ask your lender whether it accepts direct payment from a wrecker and confirm the payment process before collection.
How do I check if a car has finance owing?
Search the PPSR using the vehicle’s VIN. The VIN is unique to the vehicle and is more reliable than using the registration number.
What if my insurance payout does not cover the loan?
Check your finance and insurance documents for GAP insurance. If you do not have GAP cover, the remaining finance may still be your responsibility.
Is voluntary surrender better than scrapping the car?
Surrendering the vehicle does not automatically clear the finance. The lender can sell the vehicle and you may still have a remaining balance.
Do I get money back when I deregister the car?
You may receive a refund for unused licence fees when you cancel the registration and return the required plates and labels. You can also ask NZTA about any RUC refund.
How long does the lender have to remove the PPSR registration?
For consumer goods, the secured party generally has 15 working days after the debt is paid to discharge the financing statement.
Need to scrap a financed car?
If your car has finance owing, do not arrange collection until you know the settlement figure and how the finance will be cleared. Contact our team for a cash offer and free car removal, and we can help you understand the next steps before the vehicle is collected.
Finance owing does not automatically stop you from scrapping your car. The key is to deal with the lender first, confirm the settlement process, and make sure the PPSR and NZTA paperwork is handled correctly.